The Tough Reality of the
Construction Industry
From rising insolvencies to delayed payments, construction businesses face serious financial and legal risks. Understanding these challenges is the first step toward protecting your business, staying compliant and securing long-term success.
ATO's Debt Collection Crackdown: What It Means for Your Business
After pausing debt recovery during COVID-19, the Australian Taxation Office (ATO) has resumed aggressive collection efforts, putting thousands of businesses under financial pressure. With over $55 billion in unpaid tax liabilities, construction businesses are among the hardest hit. The ATO is now issuing Director Penalty Notices (DPNs), making company directors personally liable for outstanding debts, further increasing insolvency risks.
- 24,000+ DPNs issued in 2023, making directors personally liable.
- ATO recovering three years of unpaid tax, straining businesses.
- Construction insolvencies surging due to debt collection and cash flow issues.
- ATO’s “soft approach” in 2022 turned aggressive in 2023.
- Debt recovery efforts increasing, with more businesses at risk in 2024.
The Reality of Construction Industry Risks
The construction industry faces high insolvency rates, payment delays, and strict regulations, making stability a challenge. Understanding these risks helps protect your business and plan for long-term success.
Rising Business Insolvency Rates
Construction has one of the highest insolvency rates, with many businesses failing due to unpaid debts and poor cash flow.
Payment Delays Impacting Cash Flow
On average, construction businesses wait over 45 days to receive payments, leading to serious cash flow issues and financial strain.
Increasing Legal & Compliance Risks
Stricter regulations mean businesses must stay compliant to avoid fines, disputes, and legal trouble that can disrupt operations.
ATO Debt Recovery & Business Risks
With $55 billion in unpaid tax, the ATO is aggressively collecting debts, putting construction companies at risk.
Legal Support Designed for the Construction Industry
We provide cost-effective, fixed-fee legal solutions tailored for construction businesses. Our approach keeps you protected, compliant, and ready for any legal challenge, so you can focus on growing with confidence.
Trusted Legal Experience
Decades of legal expertise in construction law.
Cost Compared to Traditional Firms
Fixed-fee legal support without expensive hourly rates.
Dedicated to Construction Businesses
Specialized legal solutions tailored for the industry.
What History Tells Us About Economic Downturns
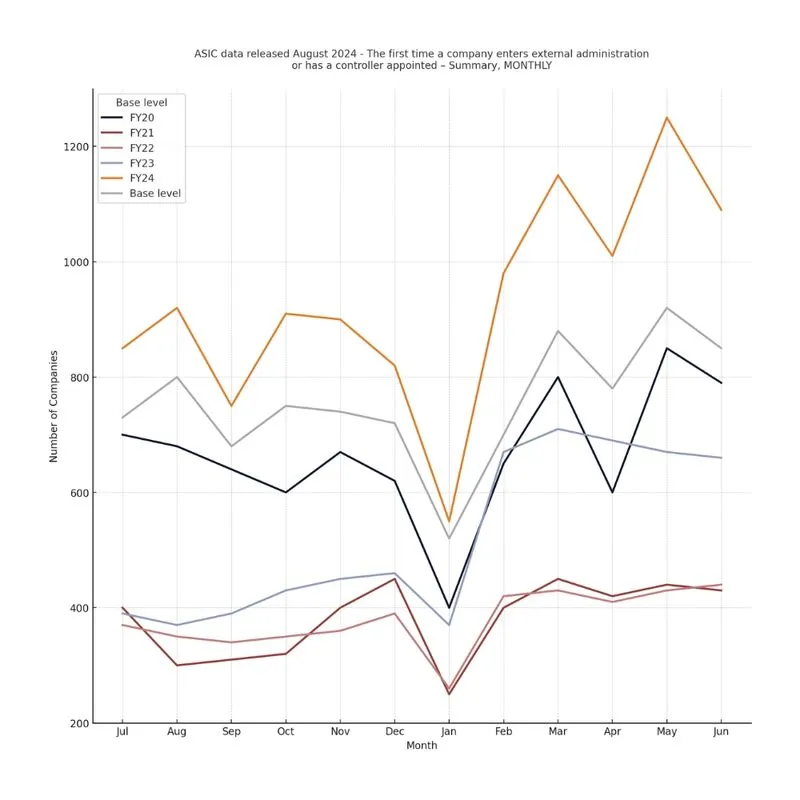
The Global Financial Crisis (GFC) and COVID-19 had long-lasting effects on business insolvencies. The GFC saw a delayed insolvency peak four years later, and we’re seeing a similar pattern post-COVID, with rising insolvencies in 2023 and beyond. Understanding these trends can help businesses prepare for financial risks before it's too late.
GFC’s 4-Year Delayed Impact
Insolvencies peaked in 2012—four years after the GFC, showing that financial crises have lasting effects.
Post-COVID Insolvency Surge
Insolvencies jumped in 2023 and 2024 as tax debts resurfaced and government support ended.
ATO’s Debt Recovery Pressure
With $52.4 billion in unpaid tax, the ATO is aggressively collecting, increasing financial strain on businesses.
Preparing for Future Insolvencies
Just like after the GFC, insolvencies will keep rising—businesses must plan ahead to stay protected.
Protect Your Business with the Right Legal Support
With rising insolvencies and aggressive debt collection, having legal protection is critical. We help businesses enforce contracts, recover payments, and avoid personal liability from ATO debt recovery actions.
Stronger Contracts
Well-drafted contracts prevent risks and disputes.
Faster Debt Recovery
Recover unpaid invoices quickly with legal support.
Compliance & Risk Protection
Avoid legal trouble by staying compliant with regulations.
ATO Dispute Defence
Legal support to fight ATO claims and protect directors.